1.1 Facts of the Case
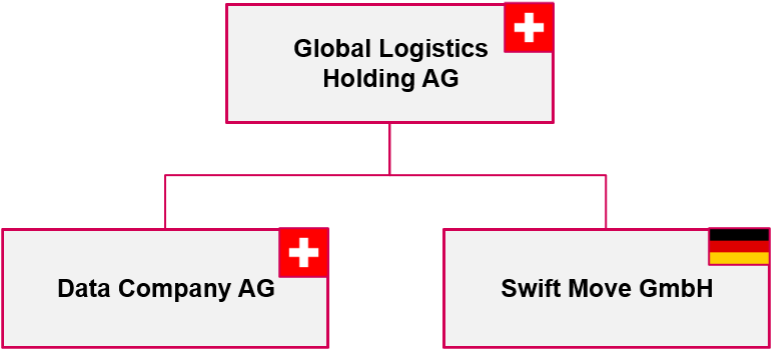
Data Company AG is a Zurich-based stock corporation whose business purpose is to collect, store, and analyze the raw data of the internationally operating Global Logistics Group. The Global Logistics Group is a globally active conglomerate in the logistics and transportation sector, consisting of various legally independent group companies. The Global Logistics Group includes, among others, the Germany-based Swift Move GmbH, an operational transportation company and sister company of Data Company AG. Data Company AG and Swift Move GmbH are wholly owned by Basel-based Global Logistics Holding AG.
The group structure can be simplified as follows:
Swift Move GmbH, as the operating company, is responsible for the physical execution of transport operations. As part of its business activities, it systematically collects various raw data, particularly regarding route paths, travel times, vehicle utilization, fuel consumption, and geographic locations. It transmits this data in unstructured form to Data Company AG. In this context, unstructured data refers to data that has been collected but has not yet been converted into a standardized data format or a form suitable for immediate analysis. This includes, for example, text and log files as well as sequential data sets that have not yet undergone any further processing or consolidation.
Data Company AG has been processing the raw data transmitted by Swift Move GmbH in a central data warehouse system since 2021. In this process, the data is cleaned, structured, and analyzed. In addition, Data Company AG incorporates raw data and analysis results from other operating companies within the Global Logistics Group into its processing. The processed data and analysis results are made available for operational use via an analytics and reporting application developed and operated by Data Company AG. This application constitutes the data product through which Swift Move GmbH can access structured analyses, reports, and data-driven insights. The development and maintenance of the analytics and reporting application incur annual costs of CHF 750,000 for Data Company AG.
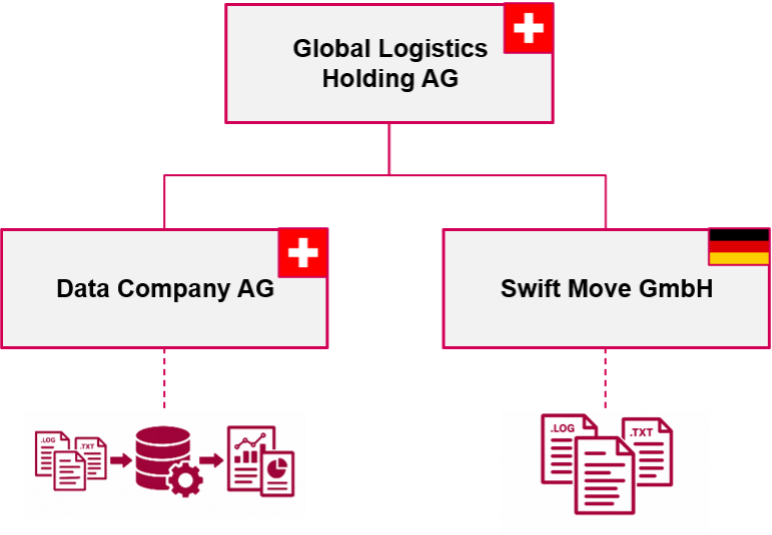
Swift Move GmbH uses the data product specifically to optimize its operational activities. In particular, the provided analyses enable the company to plan routes more efficiently, reduce mileage and fuel consumption, increase vehicle utilization, and avoid empty runs. In this way, operating costs can be reduced and existing capacities utilized more efficiently. In addition, Swift Move GmbH benefits from Data Company AG’s group-wide data infrastructure. By incorporating data and analysis results from other operating group companies, the company can, among other things, conduct benchmarking analyses, identify best practices, and apply them to Swift Move GmbH’s business operations. The insights gained from the data product can also be used in customer acquisition and retention efforts; for example, Swift Move GmbH can offer more competitive quotes, shorter delivery times, or greater planning reliability.
The economic impact at the Swift Move GmbH level can be summarized as follows:
| Cost savings | | Revenue growth | | | ------------------------- | ----------- | ----------------------------- | ----------- | | Optimized route planning | CHF 300,000 | Customer acquisition | CHF 400,000 | | Reduction in empty runs | CHF 250,000 | Customer retention | CHF 150,000 | | Higher vehicle utilization | CHF 200,000 | Benchmarking & best practices | CHF 100,000 | | Total | CHF 850,000 | Total | CHF 550,000 |
There is no specific intercompany agreement between Data Company AG and Swift Move GmbH that legally or financially governs the transfer of raw data or the provision of the data product and analysis results. Although there is a general intercompany service agreement within the group that governs, in particular, the provision of intra-group services as well as the use and licensing of intellectual property (IP) rights, However, the data transfer and the provision of the data product are not covered by this agreement and are not expressly addressed in the Service Agreement, either from a legal or a compensation perspective. Accordingly, these services are currently provided without a specific contractual basis and without separate compensation.
1.2 Questions
- Does the transfer of the processed data, including the analysis results and tools (data product), from Data Company AG to Swift Move GmbH constitute a service of monetary value?
- If so, which company is the beneficiary of the service?
- If so, what is the value of this benefit in kind?
- As part of an internal audit in 2026, management concludes that it wishes to proactively address the matter with the FTA and retroactively report the benefits in kind dating back to 2021. What specific steps must Data Company AG take?
- What is the withholding tax refund situation at the Swift Move GmbH level?
2.1 Facts
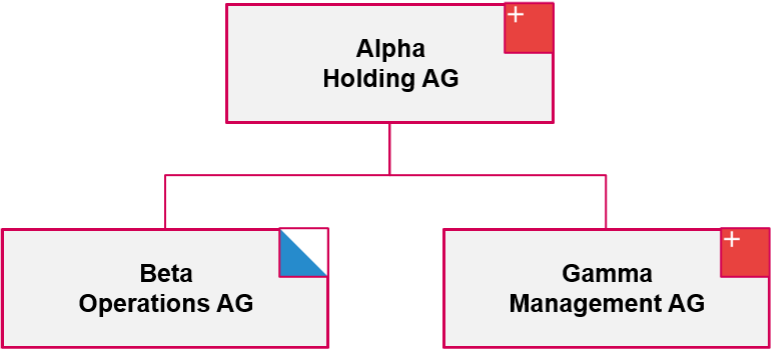
Gamma Management AG, headquartered in the canton of Schwyz, provides intra-group management and support services to its sister company, Beta Operations AG, headquartered in the canton of Zurich. Both companies are wholly owned by Alpha Holding AG, which is based in the canton of Schwyz. For these management and support services, Gamma Management AG charges Beta Operations AG annual management fees totaling CHF 500,000.
As part of a tax audit, the Zurich Cantonal Tax Office determines that the management fees charged for the years 2022 through 2025 do not meet the arm’s-length principle and constitute a monetary benefit in favor of Gamma Management AG. The following amounts are offset against Beta Operations AG’s taxable income:
| Benefits in Kind | | | -------------------- | ----------- | | Year 2022 | CHF 100,000 | | Year 2023 | CHF 80,000 | | Year 2024 | CHF 120,000 | | Year 2025 | CHF 100,000 | | Total | CHF 400,000 |
Beta Operations AG does not dispute the monetary benefits for income tax purposes, and the assessments become final in 2026. Immediately after the assessments become final (still in 2026), Beta Operations AG reports the monetary benefits using Form 102 and pays the withholding tax owed, including late payment interest, in accordance with the Federal Tax Administration (ESTV). In addition, the withholding tax is passed on to Gamma Management AG.
2.2 Question
For which tax periods can Gamma Management AG claim a refund of the withholding taxes (assuming that the other refund requirements are met and the reporting procedure does not apply)?
3.1 Facts
Second Thought AG, headquartered in Zurich, is wholly owned by Peter Müller, a resident of Zurich. Based on the 2025 annual financial statements, the annual general meeting on April 15, 2026, resolves to distribute a dividend to Peter Müller. No specific due date is set. The approved dividend is not paid out initially.
On June 20, 2026, the General Meeting (i.e., Peter Müller) revisits its decision and, at an extraordinary General Meeting, resolves to rescind the resolution on the appropriation of profits adopted on April 15, 2026. At this point, the dividend has not yet been paid out.
3.2 Questions
- When does the withholding tax liability on the dividend arise?
- Can the accrual of the withholding tax liability be “reversed” by making a corresponding contribution to Second Thought AG in the same amount?
- What is the relevance of the cancellation practice with regard to COVID-19 loans and COVID-19 hardship payments?
4.1 Facts
Mr. Arthur Mayer is a successful entrepreneur residing in the Canton of Zurich. He is the sole shareholder of Mayer Holding AG, which in turn is the sole shareholder of the operating company Mayer Maschinenbau AG. Both companies have their tax domicile in the Canton of Zurich.
Mayer Maschinenbau AG is engaged in the development, manufacture, and sale of machinery and equipment for industrial production.
In 2018, Mayer Holding AG sold all of its shares in Mayer Maschinenbau AG to the independent competitor AG for a purchase price of CHF 15 million. In addition, the share purchase agreement provided for purely performance-based earn-out payments for the years 2019, 2020, and 2021, the share purchase agreement provided for purely performance-based earn-out payments, the amount of which was contingent on the future business performance of Mayer Maschinenbau AG. In the share purchase agreement, Mayer Holding AG (as the seller) provided various warranties and indemnities.
After the signing and closing were completed, but still in 2018, Mr. Arthur Mayer signed an assignment agreement with Mayer Holding AG, whereby all rights and obligations under the share purchase agreement were assigned to Mr. Arthur Mayer personally. The assignment was made without compensation.
Subsequently, the company recorded positive business performance, following which Mr. Arthur Mayer received the following earn-out payments:
| 2019 | CHF | 200,000 | | --------- | ------- | ----------: | | 2020 | CHF | 300,000 | | 2021 | CHF | 250,000 | | Total | CHF | 750,000 |
In his personal tax returns, Mr. Arthur Mayer took the position that the earn-out payments should be classified as personal capital gains. He listed this accordingly in the comments section of each tax return, specifying the respective amount.
In 2023, an audit of the 2018–2022 financial records was conducted. The FTA took the view that there was a monetary benefit totaling CHF 750,000 from Mayer Holding AG to Mr. Arthur Mayer, which was subject to withholding tax.
4.2 Questions
- Is the FTA’s position correct both regarding the existence and the amount of the benefit in kind?
- Can the withholding tax obligation be fulfilled by filing a report instead of making a payment, and from which perspective is filing a report more advantageous?
- After submitting Form 112 to apply for the reporting procedure, the FTA sends the taxable company a letter, including an invoice, stating why the reporting procedure is not approved and that withholding tax must therefore be paid within 30 days using the enclosed QR payment slip. No information on legal remedies is included. Is the invoice a challengeable decision that triggers a time limit?