- Individuals
International Mobility
Note: This language version is an automatically generated translation. The text may therefore contain linguistic and terminological errors.
view in original language (German)Note: This language version is an automatically generated translation. The text may therefore contain linguistic and terminological errors.
view in original language (German)This seminar examines the tax and residency law aspects of the international relocation of high-net-worth individuals to Switzerland. The focus is on the requirements for the relocation of EU/EFTA and third-country nationals, taxation based on actual expenses, and the implications of changes in residential property and individual tax laws. In addition, the tax implications of various asset structures—such as holding companies, family foundations, and trusts—are analyzed prior to relocation using practical case studies.
Mukhtar Hassan would like to establish his residence in Switzerland at the end of 2026. He was born on August 1, 1990, in London (UK). He is a Saudi Arabian national and a Muslim. He has also held a Maltese passport for several years. Mr. Hassan is single and has no children. He currently lives in Saudi Arabia but also spends a lot of time in the U.S., France, and the U.K.
Mr. Hassan has family ties to Switzerland. His grandfather lived in Zurich for several years and later spent his vacations regularly in St. Moritz. Even as a child, Mr. Hassan traveled repeatedly to the canton of Graubünden with his father. He has also vacationed in other regions of Switzerland, such as Zermatt. In Switzerland, he enjoys skiing and hiking. He has friends in the Upper Engadine. He intends to take up residence in St. Moritz.
Mr. Hassan is financially independent. His assets consist mainly of financial investments such as hedge funds, stocks, and private equity, as well as real estate abroad. He also owns various works of art. He regularly receives gifts from his father in Saudi Arabia and from his mother in the United Kingdom.
Mr. Hassan leads a secluded life and is not active on social media. He travels frequently to pursue his hobbies: skiing, fishing, horseback riding, and flying. He has no plans for extended stays abroad. Despite his travels, he intends to return regularly to Switzerland, where he plans to make his primary residence.
Ferran Lopez (born in 1966), his wife Claudia (born in 1972), and their son Juan (born in 2010) are Spanish citizens and live in Barcelona. They plan to take up residence in St. Moritz in mid-2027, where Ferran Lopez has owned a condominium for years. Neither Ferran Lopez nor his wife Claudia will be engaged in gainful employment in Switzerland. Juan will attend the Lyceum Alpinum in Zuoz. Afterward, he will study mathematics at ETH Zurich.
Ferran Lopez is interested in the lump-sum taxation system in the canton of Graubünden. His net worth amounts to approximately CHF 100 million. In addition to foreign assets, Ferran Lopez owns the following Swiss assets:
Ferran Lopez expects the account and the securities portfolio at UBS AG to generate income of CHF 200,000 in the calendar year 2026, after deducting allowable administrative expenses. Furthermore, he anticipates a dividend from FLCM AG of CHF 400,000. The imputed rental value of the apartment in St. Moritz is CHF 80,000 (or CHF 64,000 after deducting the flat-rate deduction for property maintenance of 20%). For the purposes of assessing this case, corresponding income from Swiss sources is assumed for the calendar year 2027.
At the request of his tax advisor, Ferran Lopez fills out the following table of living expenses:
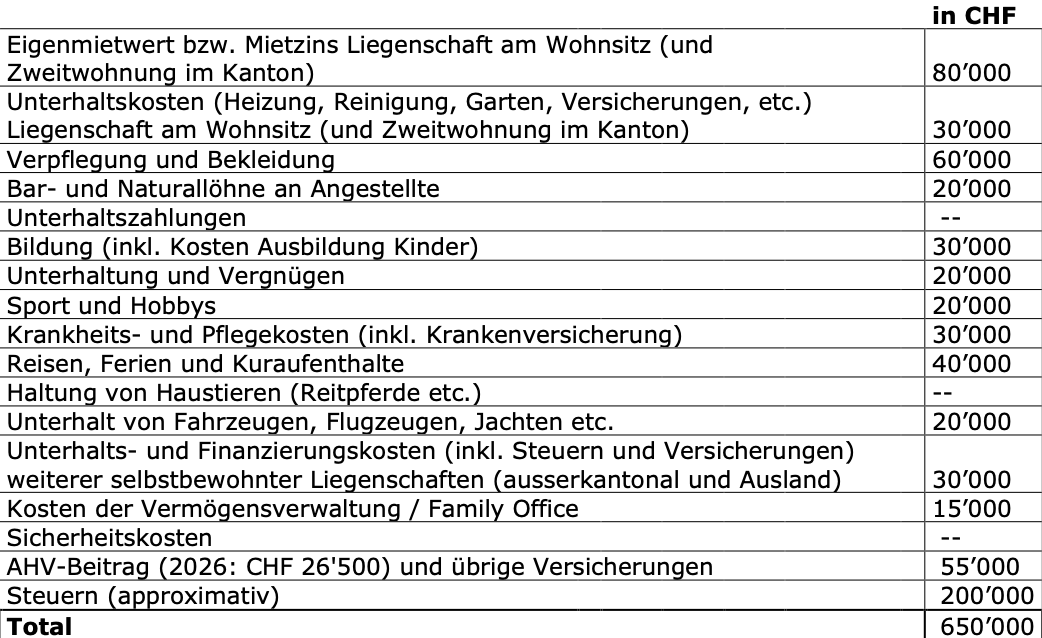
The year is 2029. The Lopez couple has had their tax residence in St. Moritz since 2027 and is taxed on an actual-expense basis. The Lopez couple’s financial circumstances have not changed from those in Case 2, except for a second home in Arosa that Ferran Lopez purchased in early 2029 and which is used by his son and brother as a vacation home free of charge. The assessed value is CHF 3.5 million; the rental value, according to the official appraisal, is CHF 65,000.
The year is 2031. The Lopez couple has had their tax residence in St. Moritz since 2027. They are taxed on an income basis.
Ferran Lopez was already very wealthy at the time of their marriage. His wife, Claudia, did not bring any significant assets into the marriage.
Peter Müller (born in 1968) is a Portuguese citizen. He has been living in Monaco for several years. He is divorced and has two adult children who live in London. Mr. Müller would like to move to Zurich as a person living off his private income in early 2027. He will not be employed in Switzerland.
Mr. Müller has previously worked as a real estate entrepreneur. He holds the properties in his private assets. He intends to sell them before moving. The proceeds from the sale, amounting to approximately CHF 80 million, are to be managed by an external asset manager. The plan is to create a portfolio consisting of stocks, bonds, and mutual fund shares.
Mr. Müller would like to secure his assets for his family in the long term. At the same time, he does not wish to relinquish control over them for the time being. During the discussion, his advisor mentions a personal holding company, a Liechtenstein family foundation, and a trust.
