1.1 Facts
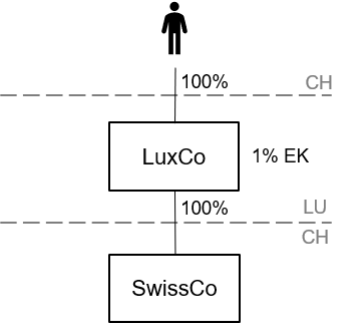
An individual residing in Switzerland indirectly holds an equity interest in a domestic corporation (SwissCo) through a Luxembourg corporation (LuxCo).
LuxCo has no employees, holds SwissCo as its sole investment, and has an equity ratio of 1%.
1.2 Question
Is this a case of treaty abuse?
2.1 Facts
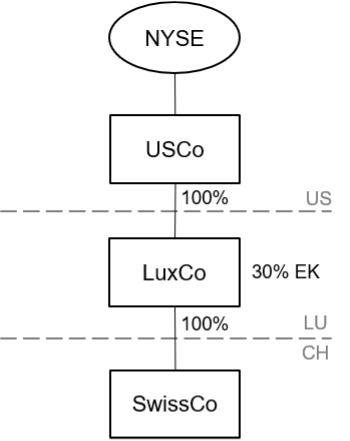
A corporation (USCo) listed on the New York Stock Exchange (NYSE) and eligible for tax treaty benefits under the DTA with the U.S. indirectly holds an interest in a domestic corporation (SwissCo) through a Luxembourg corporation (LuxCo).
LuxCo has no employees, holds SwissCo as its sole investment, and has an equity ratio of 30%.
2.2 Questions
- How should the facts be characterized (simple/qualified treaty shopping, rule shopping, or a combination of rule and treaty shopping)?
- Does LuxCo have the necessary substance to claim a full exemption from withholding tax on dividends from SwissCo?
3.1 Facts
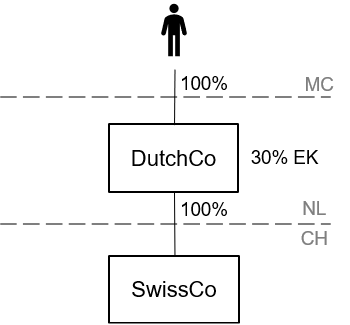
A natural person residing in Monaco indirectly holds an interest in a domestic corporation (SwissCo) through a Dutch corporation (DutchCo).
DutchCo employs no staff, holds SwissCo as its sole investment, and has an equity ratio of 30%.
3.2 Questions
- How should the facts be classified (simple/qualified treaty shopping, rule shopping, or a combination of rule and treaty shopping)?
- Does DutchCo have the necessary substance to claim a full exemption from withholding tax on the dividends from SwissCo?
4.1 Facts
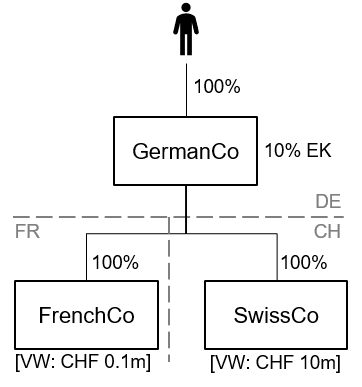
An individual resident in Germany indirectly holds an interest in a domestic corporation (SwissCo) through a German corporation (GermanCo).
GermanCo has no employees, has an equity ratio of 10%, and, in addition to SwissCo, holds another stake in a corporation in France (FrenchCo).
While SwissCo has a market value of CHF 10 million, FrenchCo is a “dormant” company with a market value equivalent to CHF 100,000.
4.2 Questions
- How should the facts be classified (simple/qualified treaty shopping, rule shopping, or a combination of rule and treaty shopping)?
- Does GermanCo have the necessary substance to claim a full exemption from withholding tax on the dividends from SwissCo?
5.1 Facts
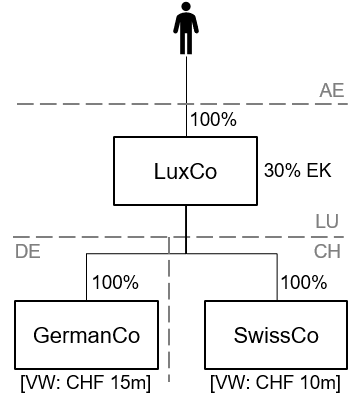
An individual residing in Dubai indirectly holds an interest in a domestic corporation (SwissCo) through a Luxembourg corporation (LuxCo).
LuxCo has no employees, has an equity ratio of 30%, and, in addition to its stake in SwissCo, also holds a stake in a corporation in Germany (GermanCo).
While SwissCo has a market value of CHF 10 million, the market value of GermanCo amounts to the equivalent of CHF 15 million.
5.2 Questions
- How should the facts be classified (simple/qualified treaty shopping, rule shopping, or a combination of rule and treaty shopping)?
- Does LuxCo have the necessary substance to claim a full exemption from withholding tax on the dividends from SwissCo?
6.1 Facts
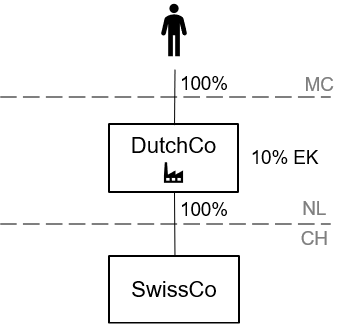
A natural person residing in Monaco indirectly holds an interest in a domestic corporation (SwissCo) through a Dutch corporation (DutchCo).
DutchCo engages in operational activities with its own staff at its own premises in the Netherlands and has an equity ratio of 10%.
6.2 Question
Does DutchCo have the necessary substance to claim a full exemption from withholding tax on the dividends from SwissCo?
7.1 Facts
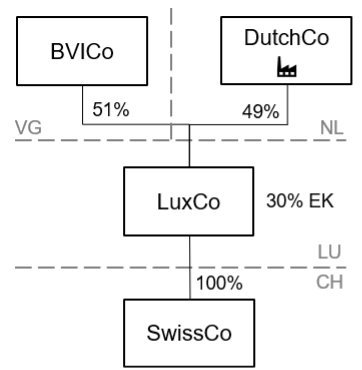
A corporation incorporated in the British Virgin Islands (BVICo) holds a 51% equity interest in a Luxembourg corporation (LuxCo). The remaining 49% is held by an operating corporation incorporated in the Netherlands (DutchCo). LuxCo, in turn, holds an equity interest in a Swiss corporation (SwissCo).
LuxCo has no employees, holds SwissCo as its sole investment, and has an equity ratio of 30%.
7.2 Question
Can LuxCo claim a full exemption from withholding tax on the dividends from SwissCo?